All Categories
Featured

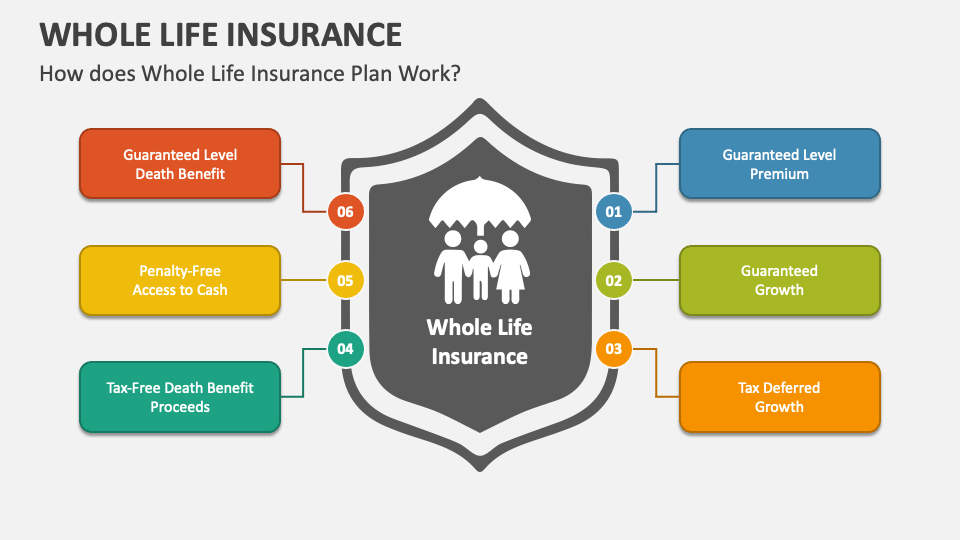
How Whole Life Insurance Works
1 Investopedia - How Whole Life Insurance Functions. Upgraded May 7, 2025. . Accessed June 18, 2026. 2 Thrivent Whole life insurance coverage: Pros, cons & who it's ideal for. Upgraded March 10, 2026. . Accessed June 18, 2026. 3 Forbes - What Is Whole Life Insurance? (& How Does it Work?) Upgraded December 18, 2024.
Accessed June 18, 2026. 4 Forbes - What Is Variable Life Insurance? Updated November 26, 2024. . Accessed June 18, 2026. Material within this short article is supplied for basic informational purposes and is not offered as tax, legal, health, or financial advice for anybody or for any particular scenario.
Aflac life plans A68000 series/Term Life: In Arkansas, Idaho, Oklahoma, Oregon, Texas, Pennsylvania & Virginia, Policies: ICC1368200, ICC1368300, ICC1368400. In Delaware, Policies A68200, A68300 & A68400.
The Mechanics of Whole Life Policies
In Delaware, Policy A68100. In New York, Policy NYR68100. B60000/Term Life: In Arkansas, Oklahoma, Pennsylvania, Texas & Virginia, Policies ICC18B60200, ICC18B60300, & ICC18B60400. Not offered in Delaware, Idaho, New York City and Oregon. Whole Life: In Arkansas, Oklahoma, Pennsylvania, Texas & Virginia, Policies: ICC18B60C10, ICC18B60100. Not readily available in Delaware, Idaho, New York and Oregon.
In Delaware, Policy Q60200M. In New York, Policy: NYQ60200M. Not available in Virginia. Whole Life: In Arkansas, Delaware & Oregon Policy Q60100M. In Idaho, Policy Q60100MID. In Oklahoma, Policy Q60100MOK. In New York, Policy: NYQ60100M. Not offered in Virginia. In AR, DE, ID, OK and VA: Policies ICC21-AFLLBL21 and ICC21-AFLRPL21; and Riders ICC21-AFLABR22, ICC21-AFLADB22, and ICC21-AFLCDR22.
In this short article, we describe what entire life insurance coverage is and compare it to term life insurance, as well as universal life and variable life insurance. Entire life insurance coverage is one type of long-term insurance coverage and is very various from term life insurance, which supplies protection for a specified duration only and does not build cash value. If term life insurance coverage is the most typical form of life insurance coverage, entire life insurance coverage is the oldest kind of permanent life insurance.
Insurance in Lake Elsinore CAThe larger your money value, the bigger the loan you can take. You can utilize your cash worth to supplement your other retirement income. Entire life insurance is the only type of life insurance coverage that ensures of the following: The death benefit will not decrease The policy will not expire as long as premiums are paid Your premiums won't
Insurance in Lake Elsinore CA
increase Your expenses will never ever increase The insurance coverage company ensures that the cash worth of your entire life insurance policy will grow gradually. determine how much your cash worth should grow based on present rates of interest, which, obviously, differ gradually. allow you to invest funds in policy subaccounts, comparable to mutual funds. Your cash worth will increase ordecrease, depending upon the efficiency of these subaccounts. What occurs if efficiency of the money value of your universal or variable life policy drops? Who needs to ante up more exceptional to keep your policy in force? You do. Neither choice is good. If you have a whole life policy, you will not have to make those horrible choices. The premium, cash value, and death advantage are all ensured. And did you know you can discover out exactly what your guaranteed premium, money value and survivor benefit will be at any point in time before you decide if it makes good sense to begin an entire life policy? Simply request a FREE, no-obligation Analysis here to take the initial step. In a way, it's like getting an income tax refund. Now, dividends are not ensured. It's imaginable an insurance provider could have a terrible, terrible, no good, really bad year . That's what the business prepares for. And every year that'smuch better than they prepared, they can pay a dividend. Get Your FREE Report! Get instant access to the FREE 18-page Unique Report that reveals how super-charged dividend paying whole life insurance lets you bypass Wall Street, fire your banker, and take control of your monetary future. You get to inform the insurance coverage company what to do with your dividend. and this just may be the neatest thing given that cupcakesyou can have them utilize your dividend to purchase more insurance for you insurance you'll never have to pay another premium for again. Believe about that! You can buy extra insurance coverage that's paid up, indicating no more premiums will be due on that additionever. If that reminds you of the 8th wonder of the worldcompound interestthat's because the idea is exactly the very same. Only paid up whole life insurance additions develop both your policy's money worth and your death advantage. You can discover more here about dividend-paying whole life insurance coverage, which many individuals find especially interesting. Term life insurance coverage premiums go upsometimes drasticallywith every new term, because much of the expense of insurance is based on how likely you are to pass away at an offered age, and as you grow older, that likelihood increases. Universal and variable insurance premiums can increase, tooagain, often drasticallyif cash worth drops dueto low rate of interest or bad financial investment efficiency. So you may be asking, "If it costs more to insure my life with every passing year, how can a life insurance coverage company assure my premiums will never go up?" The answer is elegantly simpleand it assists discuss why whole life insurance coverage is more pricey than term insurance coverage in the early years of the policy.

Latest Posts
The Mechanics of Whole Life Coverage

Comparing Term and Whole Life Insurance Basics
Smart Financial Strategies with Modern Life Insurance