All Categories
Featured
Understanding How Whole Life Insurance Works for Wealth
Navigating US Medicare Benefit Options and Seniors
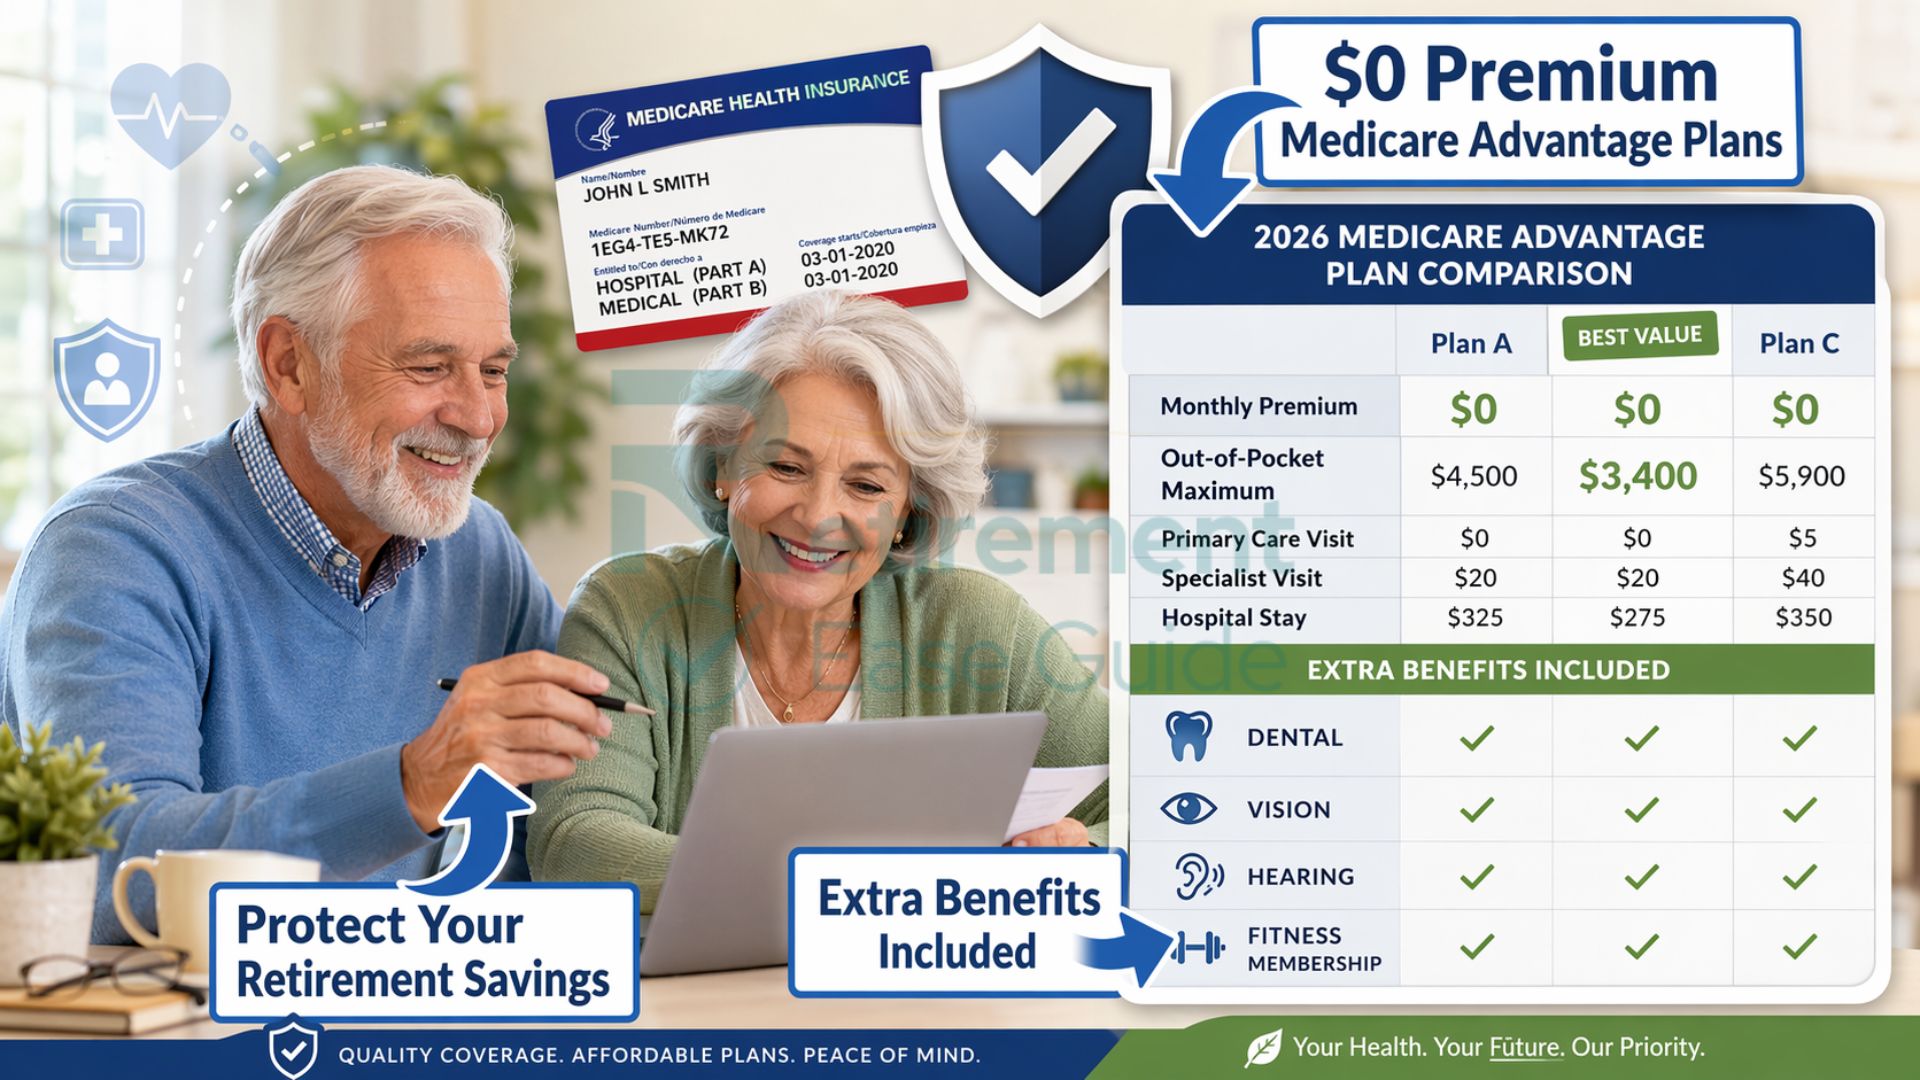
Affordable Individual Health Insurance Quotes in the US

Choosing 2026 Medicare Options
Table of Contents
Readily Available Development OptionsUnderlying Charge StructureParticipating Loan RatesCompany Credibility (since much of the above will not be guaranteed)Considering that IUL cap rates, participation rates, and loan rates have actually been a moving target fluctuating hugely, we did not want to publish real numbers just to have them end up being outdated a month or 2 later on.
Indexed Universal Life policies include charges, caps, participation rates, spreads, policy charges, and loan danger. Policy loans and withdrawals may reduce money worth and death advantage, might trigger the policy to lapse, and may develop taxable earnings if not handled properly.
Updated September 13, 2026Searching for the "best IUL business" or the "finest IUL policies for cash build-up" in 2025? You're not alone. Indexed Universal Life (IUL) insurance has acquired significant attention as a monetary tool that combines a death advantage with the potential for cash value development linked to market indexes, typically pitched as an element of a retirement technique.
Protecting Family Wealth with Term Life Insurance
The perfect policy and business depend completely on your distinct financial objectives, risk tolerance, health, and timeline. And if you are arranging an SBA loan for your organization, our guide to Life insurance coverage for an SBA loan describes how lending institutions see life coverage along with the debt. Comprehending IUL needs navigating a landscape of caps, floorings, participation rates, fees, and complex illustrations.
That's where goal, independent guidance becomes important. Invite to Insurance Coverage By Heroes. We're an independent insurance coverage company founded by a former first responder and military partner, and staffed by specialists with backgrounds rooted in public service. Our objective isn't just to offer insurance; it's to serve and educate our clients, helping them browse complicated monetary items like IUL.
This independence permits us to objectively shop the market, compare the finest IUL products offered, and tailor coverage specifically to your specific needs and goals. We think in discovering the best suitable for you, not pressing a one-size-fits-all solution. Our universal life insurance guide describes the wider choices in this category.
Direct Insurance Advice for Choosing 2026 Coverage
At its core, Indexed Universal Life is a kind of irreversible life insurance coverage policy. Unlike term insurance, which covers you for a specific period, long-term policies like IUL are created to last your whole lifetime, provided premiums are paid and the policy stays in force. IUL policies have numerous crucial elements: This is the main function of any life insurance policy.
IUL provides flexibility in death benefit amounts, which can sometimes be adjusted gradually. A part of your premium payments goes into a money value account within the policy. This account grows on a tax-deferred basis. This suggests you do not pay taxes on the gains as they accrue. This is the defining function of IUL.
Insurance in Huntington Beach CAYou are not straight purchasing the index itself. Insurance provider use various techniques to calculate the interest based on index performance. Typical methods include yearly point-to-point, month-to-month point-to-point, or monthly averaging. The approach utilized can significantly affect the interest credited. This portion determines just how much of the index's favorable motion is used to calculate your interest credit.
Cheap Individual Health Insurance
Some policies offer 100% or even higher participation rates, but this typically features other trade-offs. The majority of IUL policies have a cap, which is the maximum rate of interest that can be credited to your cash value in an offered duration, despite how high the chosen index carries out. If the index gains 15%, the involvement rate is 100%, however the cap is 9%, your cash worth would be credited with 9% interest (before charges).
Discovering the best IUL provider often includes comparing present and historic cap rates, but this is simply one piece of the puzzle. This is an essential protective feature of IUL. The flooring is the minimum interest rate your policy can make, even if the connected index experiences losses. The majority of frequently, the floor is 0%.
Some policies may provide a flooring slightly above 0%, like 1%. Like other universal life policies, IUL uses flexibility in premium payments. You can frequently change the quantity and frequency of your payments within particular limitations, although paying inadequate premiums can threaten the policy's longevity and money value development. It's instantly clear that the interplay in between these elements creates substantial variation amongst the IUL policies offered by different business.
An independent agency like Insurance coverage By Heroes is important for comparing these complex information across several leading IUL suppliers. The search keywords "best IUL for cash accumulation" and "best IUL for retirement" highlight this common interest.

Latest Posts
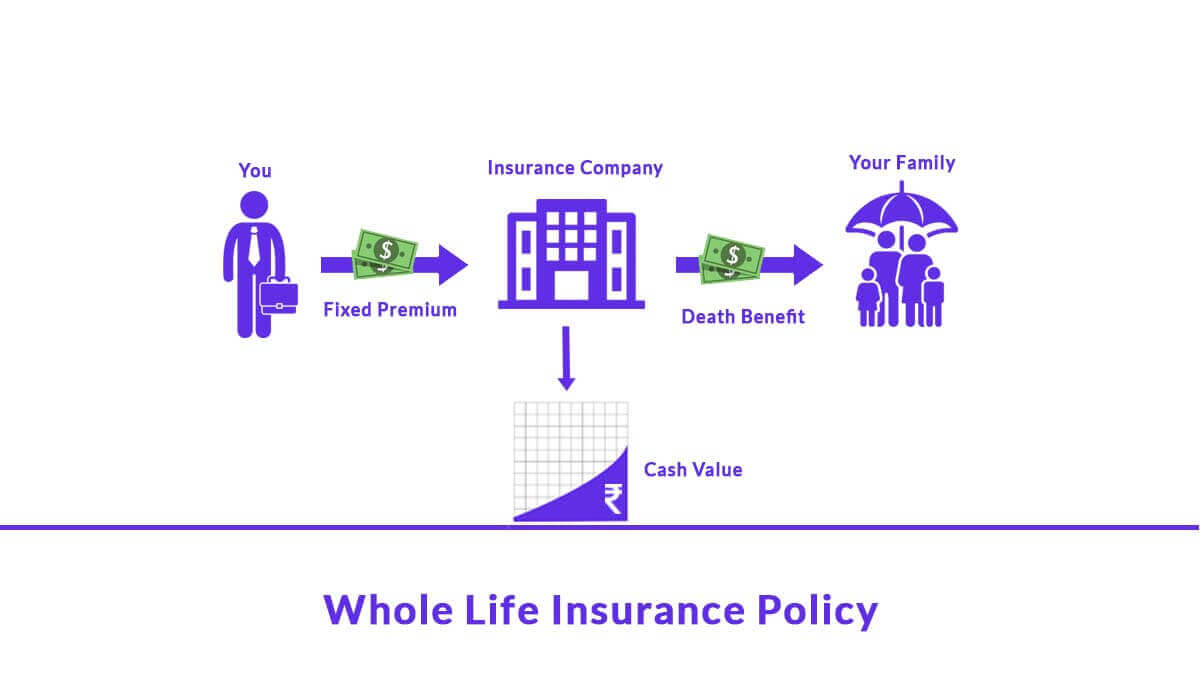
Understanding How Whole Life Insurance Works for Wealth
Individual Health Insurance Plans for Families
Navigating US Medicare Benefit Options and Seniors